Mortgage Agent · Ontario · FSRA M26001018

The mortgage that fits your real life.
Not just a rate.

I am Vishvesh Patel, a mortgage agent with Centum Financial Services Limited Partnership. I shop your file across multiple lenders and explain every step in plain English. In most standard mortgages you pay nothing — the lender pays me.

5.0 ★Google rating
13 areasGTA & Ontario served
4 languagesEnglish · Hindi · Gujarati · Punjabi
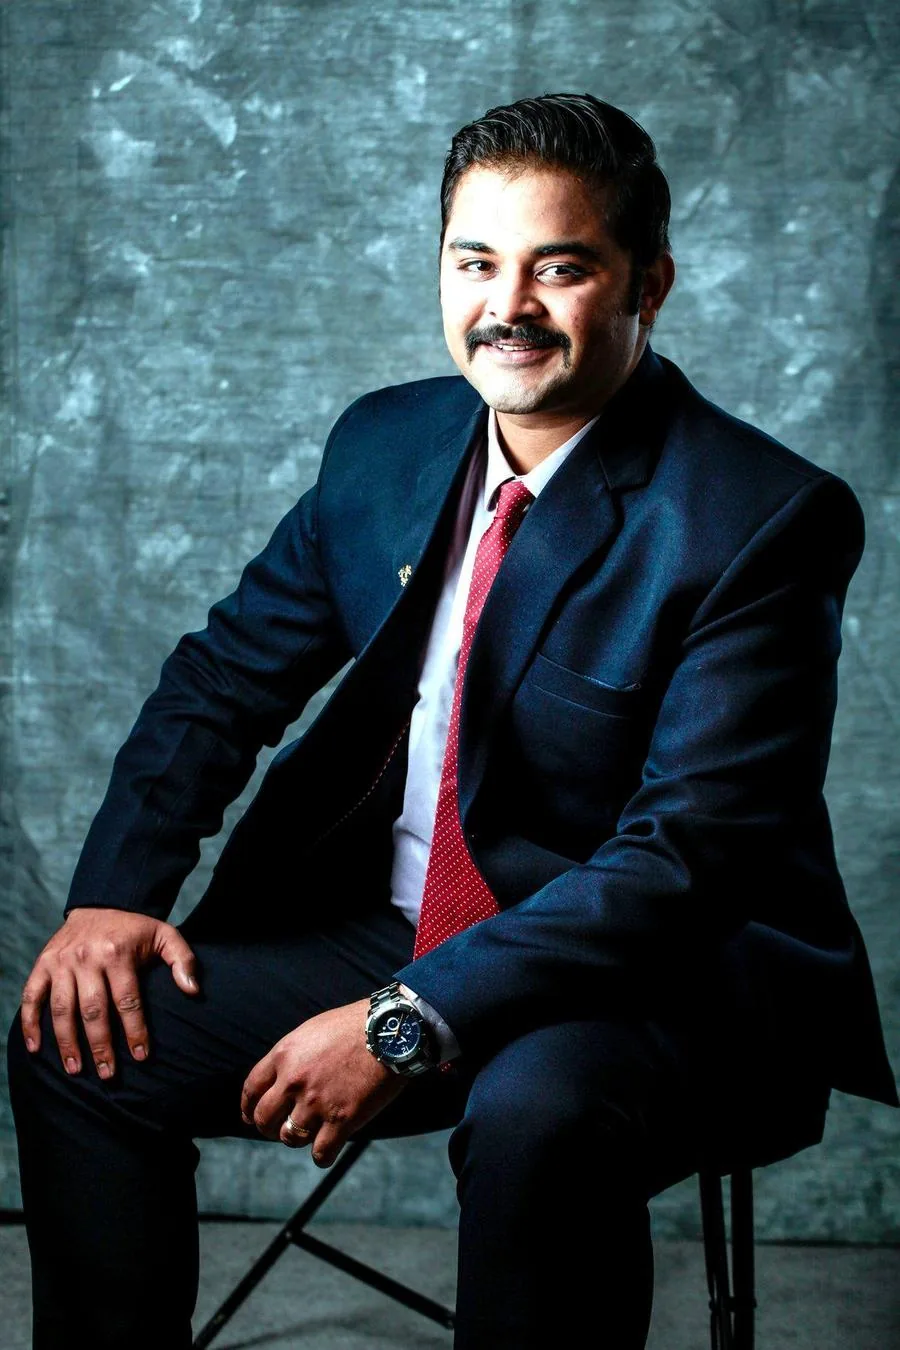
Vishvesh Patel, Mortgage Agent in Ontario
Evenings & weekendsHouses don't wait for business hours
MARKET PULSE · OCT 19, 2026 Bank of Canada policy rate 2.25% Prime rate 4.45% September CPI 3.1% year over year Next Bank of Canada decision October 28 What it means for your mortgage — ask me
Market Pulse

Today's market, in plain English

A quick read on rates and the market. The policy rate below is a live feed from the Bank of Canada; the other figures are snapshots I check and update myself.

Snapshot · Oct 19, 2026

Bank of Canada holds at 2.25%

Policy rate steady at 2.25%, prime at 4.45%. Next decision October 28. If you are renewing soon, this is the window to get your file shopped — not the month after.

Source: Bank of Canada · updated by Vishvesh
Snapshot · Oct 19, 2026

September inflation: 3.1%

CPI came in at 3.1% year over year. Above target, but the trend matters more than one print. For buyers, the takeaway is simple: get pre-approved on today's numbers, not on hope.

Source: Statistics Canada · updated by Vishvesh
Snapshot · Oct 19, 2026

Next rate decision: October 28

Most watchers expect a hold, but nobody knows for sure. What you control is your file: paperwork ready, credit checked, down payment in place. When the announcement lands, ready buyers move first.

Source: Bank of Canada schedule · updated by Vishvesh
Start here

The short answers

The three questions almost every buyer asks first.

01

How much down payment?

5% on the first $500,000, 10% on the portion to $1M, 20% beyond $1M.

Full guide →
02

Does a broker cost you anything?

In most standard mortgages, you pay nothing. The lender pays the broker.

More in the FAQ →
03

Newcomer, no credit history?

Yes, you can buy. Newcomer programs accept alternative credit.

Newcomer guide →
Vishvesh Patel smiling in a suit
About me

A straight answer, and someone who picks up the phone.

I am Vishvesh Patel, a Mortgage Agent with CENTUM, licensed by FSRA in Ontario (licence M26001018, Agent Level 1). I work with buyers from across Canada who are buying in Ontario — first-time buyers, newcomers, families renewing or refinancing, and business owners.

Outside mortgages, I am a District Leader at Manitoba Hydro, where I lead a field team of 22+ people. Before that, I worked as a Sales Associate at Home Depot. Running large teams and serving customers on a store floor taught me the same thing: people want a straight answer and someone who picks up the phone.

I am also a co-founder of Akaount, a bookkeeping, payroll, and tax business. That means I read financial statements the way business owners write them — useful when your mortgage file is self-employed or commercial.

500+Clients helped and counting
22+Field team led at Hydro
4Languages served
Who I help

If this is you, we should talk

First-time buyers

Your first home, step by step, with nothing sprung on you at closing.

Newcomers to Canada

No Canadian credit history does not mean no mortgage.

Renewals & switches

Your bank's renewal letter is an offer, not advice.

Refinancing

Unlock equity, consolidate debt, or fund a renovation — with the numbers first.

Bank said no

A decline at one bank is not the end of the road.

Pre-approvals

Know your real number before you shop.

Self-employed

Your income is real. We prove it the way lenders want to see it.

Investors

Rental and investment properties, structured properly from the start.

Commercial & business

Financing for commercial properties and business purchases in Ontario.

Down payment calculator

Move the slider. Three numbers, no email required.

$700,000
$45,000Minimum down payment
$10,500Closing costs · low (1.5%)
$28,000Closing costs · high (4%)

Minimums follow the insured-mortgage tiers: 5% on the first $500,000, 10% on the portion to $1 million, 20% beyond $1M. Closing costs are estimates — your lawyer gives the final number. General information, not advice.

Services

Residential and commercial, across Ontario

⌂

Residential mortgages

  • Purchases — first home or next home
  • Pre-approvals with a rate hold
  • Renewals and switches
  • Refinancing
▦

Commercial & business mortgages

  • Commercial purchases
  • Commercial refinances
  • Commercial renewals
  • Business purchase financing

Either way, your file is shopped across multiple lenders through CENTUM — banks, credit unions, and monoline lenders — so you see real options, not one lender's menu.

How it works

Three steps. No maze.

01

Tell me your goal

One conversation, by email, phone, or message, in plain English.

02

I shop your file

Multiple lenders, real numbers, side by side.

03

You pick, I close it

You choose. I handle the paperwork through to closing day.

Watch: From Dream to Keys

Prefer reading? Mortgages, Explained Simply (PDF)

For realtors

Partner with me

Your clients deserve a mortgage partner who protects your deal and your reputation. Send me the file, and I treat your client like my own. Residential and commercial referrals welcome.

Contact me
  • Fast pre-approvals, so your buyers shop with a real number
  • Clear communication — you hear about problems early, not at closing
  • Evenings and weekends, because offers do not wait
FAQ

Answered in plain English

Tap any question to open the answer.

How much down payment do I need to buy a home in Ontario?+

For an insured mortgage in Ontario, the minimum is 5% on the first $500,000 of the purchase price, 10% on the portion from $500,000 to $1 million, and 20% on homes $1 million and up. These are minimums. A bigger down payment means a smaller mortgage and lower monthly payments.

Can I buy a home in Ontario with no Canadian credit history?+

Yes, it is possible. Some lenders accept alternative credit, like 12 months of on-time rent, utility bills, and cell phone bills, plus an international credit report or a reference letter from your bank back home. Newcomer mortgage programs exist for exactly this situation. The paperwork matters more than the score.

What is a mortgage pre-approval, and does it guarantee financing?+

A pre-approval tells you how much you can likely borrow and usually holds a rate for 90 to 120 days. It is not a guarantee. Final approval still depends on verifying your income, your documents, and the property. Get it before you shop, not after you fall in love with a house.

Should I use a mortgage broker or go straight to my bank?+

A bank can only offer you its own products. A broker shops your file across many lenders, including banks, credit unions, and monoline lenders, and finds the one that fits your situation. If your file is straightforward, both can work. If it is anything unusual, a broker has more places to go.

Does a mortgage broker cost me anything?+

In most standard residential mortgages, you pay nothing. The lender pays the broker. Fees can apply in complex cases, like private lending or very low credit files. Ask up front. If there is a fee, you should hear about it before you commit, not at closing.

What is the mortgage stress test?+

The stress test means you qualify at a rate higher than your actual contract rate. Currently that is the higher of your contract rate plus 2%, or 5.25%. It is the government's way of checking you can still pay if rates rise. It applies to most new mortgages and refinances.

How much are closing costs in Ontario?+

Plan for 1.5% to 4% of the purchase price on top of your down payment. That covers land transfer tax, legal fees, and adjustments. Buyers who budget only for the down payment run out of money at the finish line. Get a written estimate from your lawyer early.

What credit score do I need for a mortgage in Ontario?+

There is no single cutoff. A higher score gives you more lenders and better rates. Some programs, including newcomer programs, can work with alternative credit if you have no Canadian score yet. What matters most is the full picture: income, debts, down payment, and payment history.

Should I sign my bank's renewal letter?+

No, not automatically. Your bank's renewal letter is an offer, not advice, and it is usually not their best rate. You can shop it, switch lenders, or negotiate. Start 120 days before your renewal date. Signing the first letter you get is how people overpay.

Do I need a stress test to renew or switch lenders?+

If you renew with your current lender and keep the mortgage the same, you typically do not need to pass the stress test again. If you switch lenders or refinance, the rules differ, and a straight switch is often simpler than a full refinance. Ask before you assume.

What documents do I need for a mortgage application?+

Most files need the same core set: photo ID, proof of income (pay stubs, T4s, and your Notice of Assessment), employment confirmation, down payment proof, and your purchase agreement if you have one. Self-employed and newcomer files need more. A clean paper trail is what gets files approved.

Can I buy a home in Ontario while living in another province?+

Yes. Buyers from across Canada buy in Ontario regularly. The lender will ask about your move plans, your employment in Ontario, and whether the home will be your principal residence. Be ready to show the paper trail for the move.

How much mortgage can I afford on a $75,000 income in Ontario?+

A rough guide is about 4 to 4.5 times your income, so around $300,000 to $337,000, before other debts. Lenders actually decide using debt ratios: your housing costs should stay under about 35% of gross income, and all debts under about 44%. Car loans, credit cards, property tax and heating costs all reduce the number. Send me your income and debts and I will run your exact figure for free.

What is the best mortgage lender for self-employed buyers in Toronto?+

There is no single best lender. It depends on how you report your income. If you show strong income on your taxes, the big banks can work. If you write off a lot, B lenders and credit unions often look at your bank statements and business income instead. I compare both sides and show you the real cost of each option before you choose.

Can a newcomer with 6 months in Canada get a mortgage?+

Yes. Newcomer programs exist for permanent residents and many work permit holders, with as little as 5% down. With little or no Canadian credit, lenders can use other proof instead, like rent payments, utility bills, or a credit report from your home country. Being in Canada 6 months is enough for many files. The key is setting up the documents early.

How long does a mortgage pre-approval take in Ontario?+

Once your documents are in, most pre-approvals come back in 24 to 72 hours. The rate hold is usually 90 to 120 days, which protects you while you shop. A pre-approval is not a final approval: the lender still checks the property and your documents again before closing.

What credit score do I need to buy a $700,000 home in Mississauga?+

For an insured mortgage, the minimum is generally 600, but most A lenders want to see 650 to 680 or higher for their best rates. Your score is only one part: income, down payment, and your other debts matter just as much. If your score is under 650, there are still options, and I will tell you honestly where you stand.

Browse the blog for more answers

Vishvesh Patel in a suit
Contact

Talk to me about your file

Evenings & weekends — reach me when you need me. English, Hindi, Gujarati & Punjabi.

✓No spam, no pressure. I read every message myself and reply in plain English — usually the same day.

Where I work

Licensed in Ontario, helping buyers from across Canada buy in Ontario.